Read a sample: 1. A Spending Plan for Retirement Income
Retirement can change the way money arrives without changing how often life asks you to spend it. The mortgage or rent still comes due. Groceries still need to be bought. A car may need a repair, a relative may need help, or an opportunity to travel may appear. Yet the dependable rhythm of a paycheck may have given way to several payments on different dates, occasional earnings, or withdrawals you must decide how to make.
A spending plan gives those dollars jobs. It helps you see what must be paid, what you want to enjoy, and what you need to hold for later. Its purpose is not to turn retirement into an exercise in restriction. It is to make your choices visible, so you can use your money with greater confidence and adjust when circumstances change.
You do not need to know every future expense before you begin. You do need a useful starting picture, a willingness to revise it, and a way to distinguish an ordinary change from a problem that calls for action.
During your working years, budgeting may have centered on a familiar question: How much of each paycheck can be spent, saved, or used to pay debt? Income may have arrived on a regular schedule, while retirement contributions and some benefits came out before the money reached your checking account.
Retirement income can be less uniform. A household might receive Social Security, a pension, part-time earnings, and transfers from savings or investments. One source may arrive monthly, another only when work is available. Some amounts may change, end, or require a decision before money becomes available to spend.
The distinction between income and available cash also matters. A payment quoted before deductions is not necessarily the amount that reaches your account. A withdrawal from an investment account may provide cash for spending, but it is also a reduction of an asset you own. Taxes, withholding, fees, and the source of a withdrawal can affect how much is available and what remains for the future.
A retirement spending plan therefore does more than divide a monthly total. It answers several practical questions:
- Which money can we reasonably expect, and when?
- Which obligations must it cover?
- How much room is there for the activities and purchases we value?
- What cash needs to remain available for bills and surprises?
- What will we change if income or spending does not match the plan?
Those questions are useful whether your income feels ample or tight. They are also useful if you have not yet retired and want to test what a different pattern of income might mean.
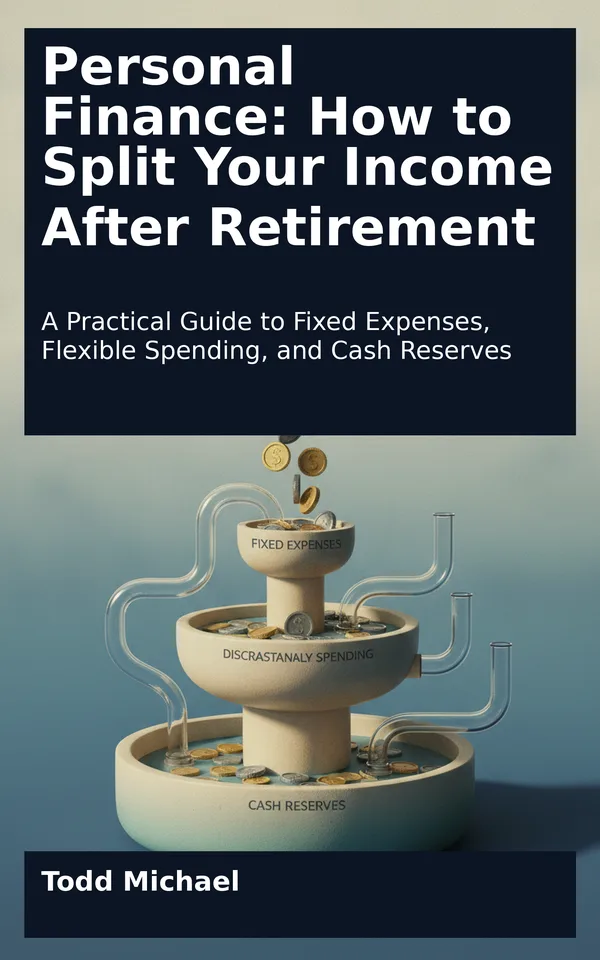
This book organizes the household plan into three groups: fixed expenses, flexible spending, and cash reserves. The groups are tools, not rigid definitions. Their value comes from helping you make decisions consistently.
Fixed expenses are the recurring commitments you generally expect to pay and cannot easily change from one month to the next. Housing payments, insurance premiums, minimum debt payments, and essential services often belong here. Some amounts are predictable; others, such as utilities, can vary even though the need to pay them remains.
Flexible spending covers expenses where you have more choice over the amount, timing, or frequency. Dining out, hobbies, gifts, entertainment, and travel may fit here. Some everyday categories contain both essential and flexible portions. Food is necessary, for example, but choices about restaurants, brands, and special occasions can change its cost.
Cash reserves are money set aside for a defined future purpose rather than assigned to current spending. A reserve might help bridge the days between a bill and an incoming payment, prepare for a known annual expense, or provide resources for an unexpected repair.
The groups work together. Fixed expenses establish a baseline. Flexible spending gives the plan room for personal priorities and adjustment. Cash reserves help prevent uneven bills or surprises from immediately disrupting the rest of the plan.
Avoid treating these labels as moral judgments. A modest hobby can be deeply important, while an expensive recurring subscription may be easy to cancel. What matters is the role an expense plays in your household and how readily you could change it.
Consider a hypothetical retired household that has $4,000 available for its monthly plan after the deductions it has already accounted for. The household makes this initial allocation:
- Fixed expenses: $2,400 per month
- Flexible spending: $1,000 per month
- Cash reserve contributions: $600 per month
The three amounts add to $4,000. That arithmetic is useful, but it does not establish that the plan is suitable. The household still needs to check whether the fixed-expense estimate is complete, whether $1,000 reflects its actual priorities, and whether $600 is enough—or more than necessary—for the reserve purposes it has identified.
Suppose $250 of the monthly reserve contribution is intended for an annual insurance bill. Over twelve months, setting aside $250 each month would accumulate $3,000, assuming the household starts before the full twelve-month period and does not use that money for something else. When the bill is paid, the payment comes from the designated reserve. It should not also be counted as a new expense in the month’s allocation.
Now suppose the same household discovers that its fixed expenses are actually $2,600. If available cash remains $4,000, it must find $200 elsewhere in the plan. It might reduce flexible spending, contribute less to reserves…